Which Services Bundle 3-Bureau Credit Reports With Monitoring?
Three-bureau monitoring does not always include the scores you need. Compare service options and understand FICO Score 8, mortgage scores 2/4/5, and FICO Auto Score 8.
By Abel | Credit.CC
You sign up for credit monitoring, open the dashboard, and see three scores. Then a mortgage lender or car dealership gives you a different number.
That does not necessarily mean either score is wrong. You may be looking at different scoring models, different credit bureau information, or scores calculated on different dates.
When comparing services that bundle three-bureau credit reports with monitoring, look beyond whether they show three numbers. Check which reports, which score versions, and which updates you actually receive.
Disclosure: This article is published by Credit.CC, which offers credit and identity protection services.
What does a three-bureau bundle include?
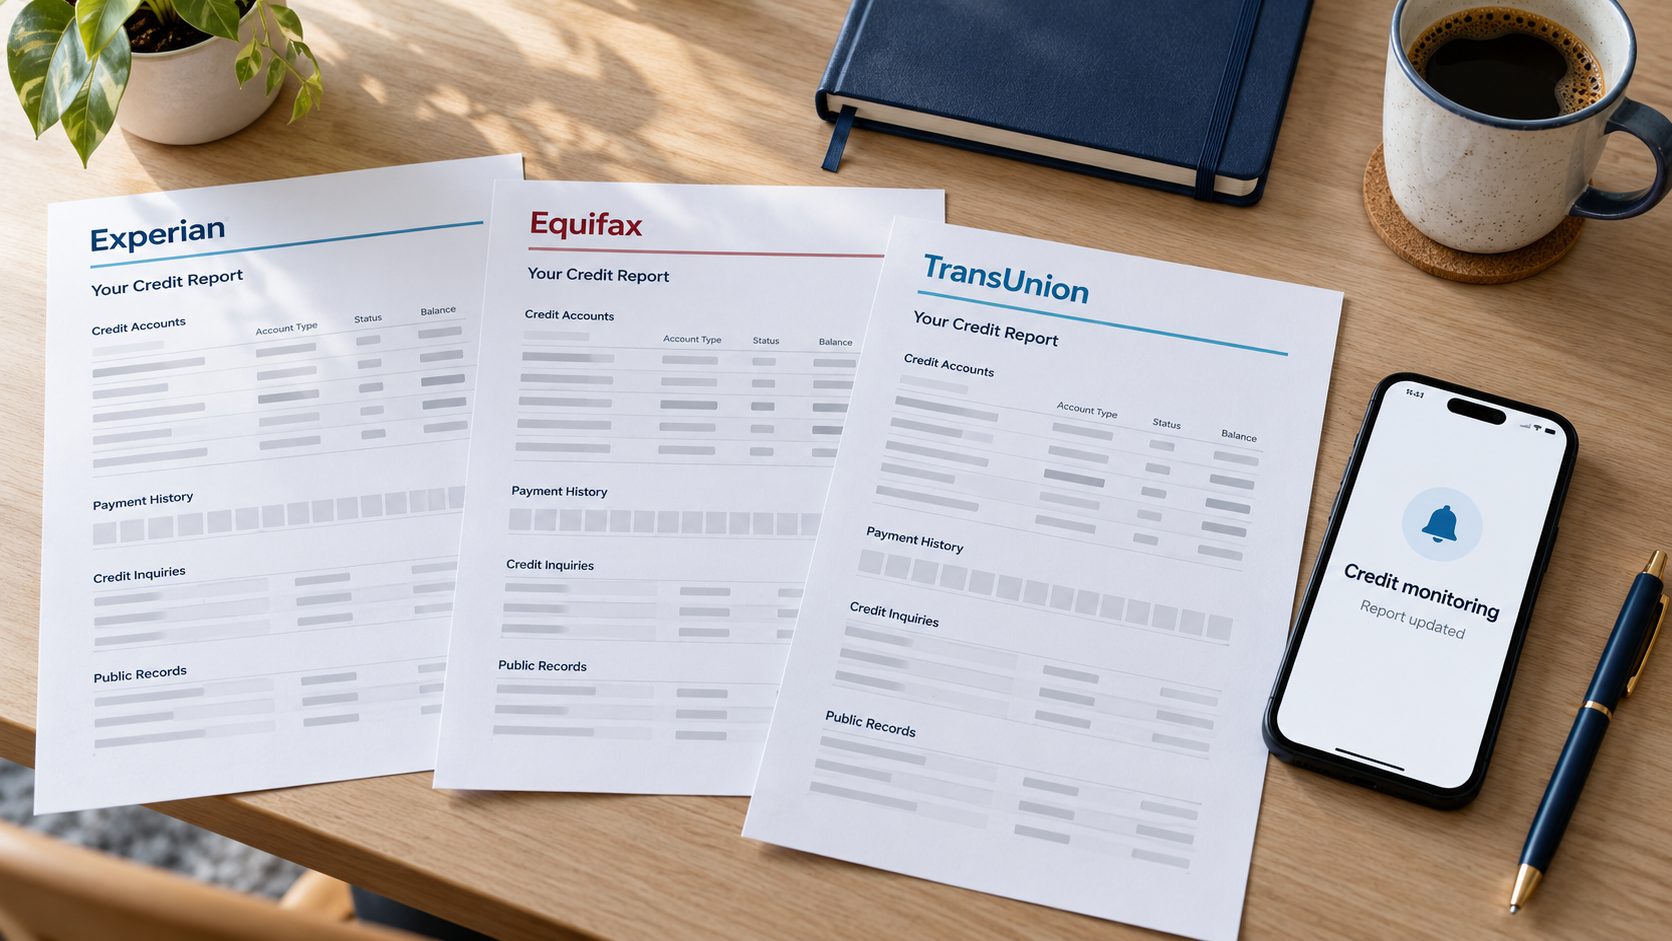
A three-bureau credit report gives you access to information maintained by Experian, Equifax, and TransUnion. Monitoring watches for certain changes in those credit files.
Report access and monitoring are separate benefits. A service can monitor daily while providing refreshed full reports less frequently. For example, TransUnion Credit Premium advertises daily three-bureau monitoring with quarterly three-bureau report and score updates.
Before subscribing, check three separate details:
- Reports: Can you view reports from all three bureaus?
- Monitoring: Are all three files monitored?
- Scores: Which scoring model and version does each score use?
Which services offer reports and monitoring together?
Several services offer this combination, although the included scores and refresh schedules differ.
| Service | Three-bureau reports and monitoring | What to check | |---|---|---| | myFICO Advanced | Includes three-bureau coverage, reports, monitoring, and multiple FICO score versions | Full updates are available every three months | | myFICO Premier | Includes three-bureau coverage, reports, monitoring, and multiple FICO score versions | Full updates are available monthly | | Experian premium membership | Offers three-bureau reports, FICO scores, and ongoing three-bureau monitoring | Verify the specific membership’s refresh schedule and additional score access | | TransUnion Credit Premium | Includes three-bureau monitoring and quarterly three-bureau reports and scores | Read the score-model disclosure; three-bureau access does not automatically mean FICO |
These are examples, not an exhaustive ranking. Check current enrollment details before purchasing.
Credit.CC also offers three-bureau credit monitoring and FICO score options. When comparing its plans and additional score purchases, distinguish the ongoing subscription benefits from any separately purchased score package.
FICO Score 8: a general credit benchmark
FICO Score 8 is a base scoring model used to assess general credit risk. Its range is 300–850.
You can have a FICO Score 8 based on Experian data, another based on Equifax data, and another based on TransUnion data. Those numbers can differ because the underlying credit files differ.
It is useful for tracking your credit, but it is not a promise of the score a particular lender will use.
FICO Scores 2, 4, and 5: the classic mortgage versions
The numbers 2, 4, and 5 identify different FICO model versions associated with specific bureaus.
| Credit bureau | Classic mortgage score version | |---|---| | Experian | FICO Score 2 | | TransUnion | FICO Score 4 | | Equifax | FICO Score 5 |
These are base FICO scores, with a 300–850 range. They are commonly grouped together as “mortgage scores,” but they are separate models rather than one score calculated three times.
Access can help you prepare for a mortgage conversation without assuming your everyday FICO Score 8 tells the whole story.
However, mortgage scoring is changing. As of October 2026, eligible Fannie Mae and Freddie Mac loans may use Classic FICO or VantageScore 4.0 under applicable requirements. Ask your lender which model applies to your loan.
FICO Auto Score 8: built for auto lending
FICO Auto Score 8 is an industry-specific model designed for auto lending. Its range is 250–900, rather than the 300–850 range used by base FICO Score 8.
Despite sharing the number 8, they are different models. A FICO Score 8 of 720 does not mean your FICO Auto Score 8 will also be 720.
Auto lenders choose which score model and bureau information they use. FICO Auto Score 8 can provide useful context before financing a vehicle, but a lender may use another version or scoring model.
Does monitoring refresh every score?
Do not assume it does.
An alert about a credit-file change is different from a newly calculated mortgage or auto score. A subscription may update one score with monitoring alerts while refreshing additional versions only when a new full report becomes available.
Ask the provider:
- How often are full reports refreshed?
- Which scores update with alerts?
- When do mortgage and auto scores refresh?
- Does an early refresh cost extra?
myFICO, for example, explains that monitored data, alerts, and score updates vary by bureau.
Choose the bundle around your next goal
For routine credit tracking, focus on bureau coverage, useful alerts, and a clear refresh schedule.
For a home purchase, ask your lender which scoring model matters before purchasing additional scores.
For vehicle financing, look for the exact auto score version included and remember that the lender makes its own selection.
A useful bundle makes those details easy to find. You should know what you are viewing, when it was calculated, and what your subscription will update next.