What Are the Best Ways to Monitor Your Family’s Credit Health?
A healthy family credit routine goes beyond checking a score. Learn how to review credit reports, protect children’s identities, and catch problems before a major purchase.
By Abel | Credit.CC
Most families have a system for keeping track of school schedules, doctor appointments, and monthly bills. Credit usually gets attention when someone needs a mortgage, a car loan, or a first credit card.
By then, an unfamiliar account or an overlooked payment can become an urgent problem.
A simple family credit routine can help you notice changes earlier and keep borrowing plans on track. It does not require everyone to check a score every day. It requires knowing what to review, whose information needs attention, and what to do when something looks wrong.
1. Start with each adult’s credit
There is no single family credit score.
Each person has an individual credit history. Getting married does not combine your scores, although a joint credit account can affect both account holders. When spouses apply for a loan together, lenders may consider both applicants’ credit.
That means one spouse’s healthy credit report does not tell you whether the other spouse’s report is accurate.
A useful starting point is for each adult to review their own reports and identify:
- Accounts they recognize.
- Outstanding balances.
- Payment information.
- Unfamiliar inquiries.
- Incorrect personal details.
Make it a shared household habit while keeping each adult in control of their own accounts and information.
2. Review all three credit reports
Checking a score is convenient. Reviewing the information behind it gives you more to work with.
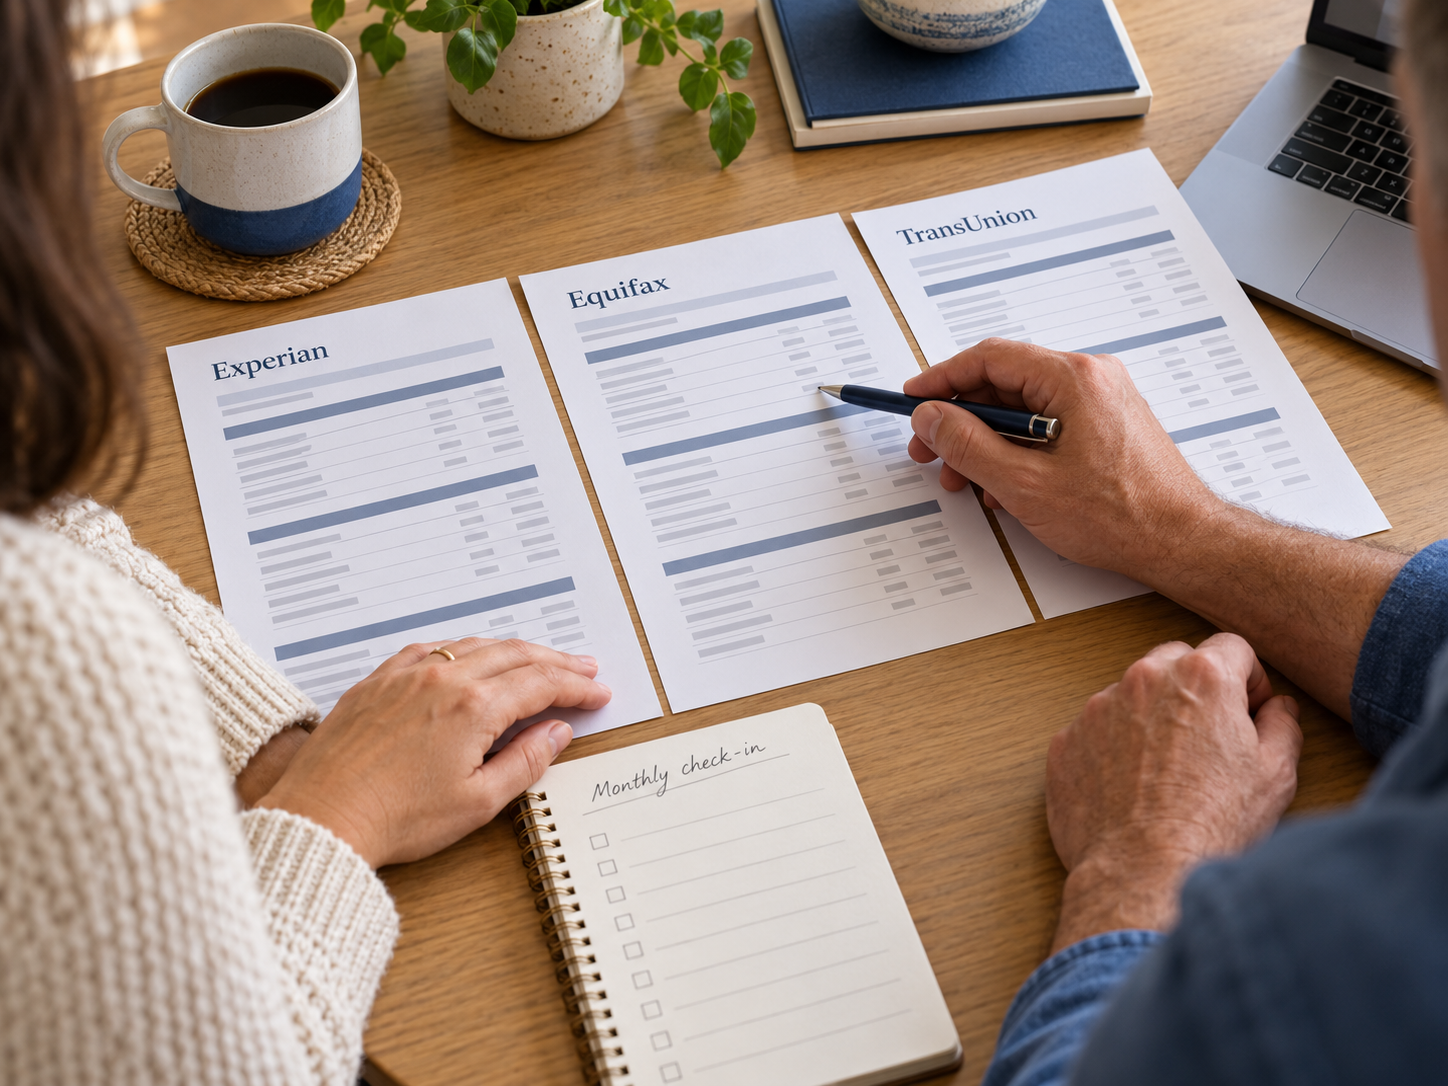
Adults can get free weekly online credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com.
You do not need to turn that availability into a weekly chore. One practical approach is to schedule a monthly household credit check and review reports more closely before a major borrowing decision.
During the review, ask:
- Is there an account I did not open?
- Is a payment marked late when I believe it was on time?
- Does a balance need a closer look?
- Is there an inquiry I cannot explain?
- Does any personal information look unfamiliar?
Keep a short record of anything that needs follow-up. A reminder with a date and next step is more useful than assuming someone will remember.
3. Watch the habits that affect credit health
Fraud is only one part of the picture. A family can recognize every account on its reports and still have credit problems caused by missed payments or rising balances.
Payment history, outstanding debt, and how close accounts are to their credit limits can affect credit scores. Paying on time and avoiding balances near your limits are useful habits.
For your household routine, consider:
- Setting payment reminders before due dates.
- Using automatic payments where appropriate, with enough money available to cover them.
- Reviewing balances before adding new recurring expenses.
- Agreeing on who is responsible for each shared bill.
A brief conversation about an upcoming payment can prevent confusion between two people who each thought the other had handled it.
4. Use alerts to bring changes to your attention
A scheduled review is useful, but you may want to hear about certain changes between check-ins.
Credit monitoring can alert you to changes in a monitored credit file. Identity monitoring may look for other signs of personal information being used. Neither guarantees that identity theft will be prevented.
Before signing up, decide which alerts would help your family and who will review them.
If you already receive notifications through a bank, employer benefit, or monitoring service, take a few minutes to understand what they cover. An alert is useful only when it reaches someone who knows what to do next.
5. Include children in your protection plan
A child does not need a credit card to need identity protection.
Children generally do not have credit reports, but there are exceptions. An authorized-user account can create a legitimate file. A file can also result from an error or identity theft. Parents and guardians can ask the three major credit bureaus to check whether a minor has a report.
For children under 16, a parent or authorized guardian can request a free security freeze with each bureau. If necessary, the bureau creates a record specifically to freeze it. This helps make it harder for someone to open credit in the child’s name.
Watch for unexpected collection notices, bills, or tax correspondence addressed to your child. Those deserve investigation rather than being dismissed as junk mail.
6. Help teens build their own routine
As teens begin managing money, explain what a credit report shows and why account information matters.
For a teen approaching adulthood, a useful conversation might include:
- How to recognize an unfamiliar account.
- Why paying on time matters.
- How to protect account passwords.
- Why a credit offer is not the same as money available to spend.
- Where to get help if something looks wrong.
At 18, help them establish their own review routine. Offer guidance while letting them manage access to their personal financial information.
7. Consider credit freezes for adults, too
Monitoring and freezing serve different purposes.
Monitoring helps bring changes to your attention. A security freeze restricts access to your credit file and can help prevent someone from opening new credit accounts in your name.
Adults can freeze and unfreeze their files for free with each of the three bureaus. Freezes do not affect credit scores, and you can still review your reports while they are in place. You may need to lift a freeze temporarily when applying for credit.
Keep the account access information somewhere secure so an upcoming application does not become a last-minute scramble.
8. Know what a family monitoring plan includes
If you prefer a paid service, compare the details for every person you intend to cover.
Ask:
- How many adults and children are included?
- Which bureaus are monitored for each adult?
- What protection is available for children?
- Who receives alerts?
- What recovery assistance is included?
- What is the ongoing cost?
Do not assume a family subscription gives every member identical features. Look for a clear explanation of adult monitoring, child protection, and any additional enrollment steps.
A manageable monthly family credit check
Set aside about 15 minutes to get started:
- Each adult reviews available credit alerts and account information.
- Check upcoming payments and discuss unusual balance changes.
- Review credit reports on your chosen schedule.
- Record anything that needs investigation.
- Confirm who will follow up and when.
Children’s protection can be handled separately: keep freeze records secure, investigate warning signs, and revisit the setup as they get older.
The best routine is one your family can maintain. Start with a clear picture of each person’s situation, put a few useful safeguards in place, and make the next check part of the calendar.